



Uganda’s fintech honeymoon is officially dead. The era of easy growth, flashy app launches, and reckless market expansion has crashed into a wall of reality.
Survival now demands ruthless scaling, actual financial sustainability, and the undeniable proof of long-term economic value.
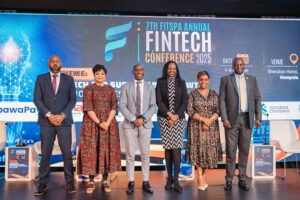
This high-stakes reckoning takes center stage at the 8th FITSPA Annual Fintech Conference 2026, colliding at the Sheraton Kampala Hotel on October 6–7 under the provocative banner: “Scaling Fintech Innovation for Inclusive Growth and a Resilient Digital Economy.”
Organized by the Financial Technology Service Providers’ Association (FITSPA), the two-day gridlock features an aggressive coalition of backers—from the Bank of Uganda and the Bill & Melinda Gates Foundation to aggressive market giants like MTN Mobile Money and Airtel Money. Over 500 power players will cram into the room. Founders, hungry investors, tight-fisted regulators, and legacy telecom operators are converging to debate a uncomfortable truth: How do we stop funding half-baked “promising solutions” and start building ruthless, commercially viable empires?

For ten years, fintech code-cutters disrupted how Uganda moves money, treating mobile wallets and digital loans like a playground. But the playground is closed. As the sector matures, a heavy question looms over every entrepreneur: What actual substance comes next?
FITSPA Managing Director Zianah Nyiramanza isn’t sugarcoating the transition. The conference exists to drag players into the brutal realities of survival.
“We are forcing a question that too many founders avoid,” Nyiramanza warns. “What does it actually take to drag an idea out of the early-stage sandbox and scale it into a cutthroat, commercially sustainable monster that serves millions?”


Nyiramanza argues that the definition of innovation has been weaponized. Coding a new app is no longer enough. True innovation now means surviving capital starvation, outmaneuvering regulators, invading hostile new markets, and desperately earning back a skeptical public’s trust.
To survive, the entire ecosystem—regulators, cutthroat investors, and legacy banks—must stop operating in silos and actively collide.
The backdrop to this gathering is grim. Across Africa, fintech founders are suffocating in a hostile growth environment defined by an absolute drought of capital, suffocating regulatory overwatch, and a desperate pressure to prove their unit economics actually make sense.
The debate will rip open the systemic flaws holding the industry back like Capital Crutch navigating investor skepticism and funding dry spells,the broken state of digital infrastructure and real nteroperability,surviving policy frameworks that often strangle innovation before it breeds and addressing the looming, volatile impact of Artificial Intelligence (AI), blockchain, and cloud dominance on financial services.
Ken Njoroge—the legendary co-founder of Cellulant—will deliver the keynote address.
Njoroge didn’t just build a startup; he survived the African tech trenches. He dragged Cellulant from a fragile mobile content hustle in 2003 to a pan-African payment behemoth dominating 35 markets. By squeezing $125 million out of European and American investors, Njoroge holds the bloody blueprint on the agonizing trade-offs, aggressive leadership, and corporate scars required to scale an African tech business. He is there to tell founders the unvarnished truth about raising cash and surviving the weight of growth.
Over two days, the conference will dissect the industry’s friction points: policy fights, capital access, consumer trust deficits, and the weaponization of AI. Beyond the networking and product showcases, the event intends to force actionable ultimatums.
In eight years, FITSPA has shifted from a polite compliance talking shop into a high-octane battleground for the future of money. The 2026 edition isn’t about celebrating milestones—it’s about demanding whether Uganda’s fintech ecosystem can stop playing small, survive its own maturity, and generate undeniable wealth.


He strongly advocates for a tax framework that acts as a runway rather than a roadblock. At recent tax compliance summits, Tumwijukye argued that while fintechs must contribute to domestic revenue, the government must explicitly build a tax environment that allows early-stage fintechs to attract investment, innovate, and safely scale without being strangled by premature taxation.
“We need the industry to own up by adopting the Industry Code of Conduct for Responsible Lending.”
According to reports by Financial Sector Deepening (FSD) Uganda, sector employment has grown rapidly, exceeding 20,000 jobs and the fintech sector contributes roughly 7% of Uganda’s national GDP.
The number of active fintech firms has climbed rapidly, reaching nearly 200 registered companies, up from roughly 70 companies a few years prior.
Driven by partnerships with telecom giants like Mtn Mobile Money and Airtel Money, electronic money transaction values surged by 28% to hit a record UGX 366 trillion, increasingly displacing physical cash


