




Imagine walking into a commercial bank in Kampala to secure a business loan, but instead of handing over land titles or car logbooks, you simply open your smartphone. You show the loan officer your digital wallet statements, your electronic transaction history, and your automated digital ledgers.
This isn’t a futuristic concept—it is the rapidly emerging reality of business in Uganda. The historical bottleneck for Ugandan small and medium enterprises (SMEs) is shifting away from a scarcity of market capital toward a critical data deficit.
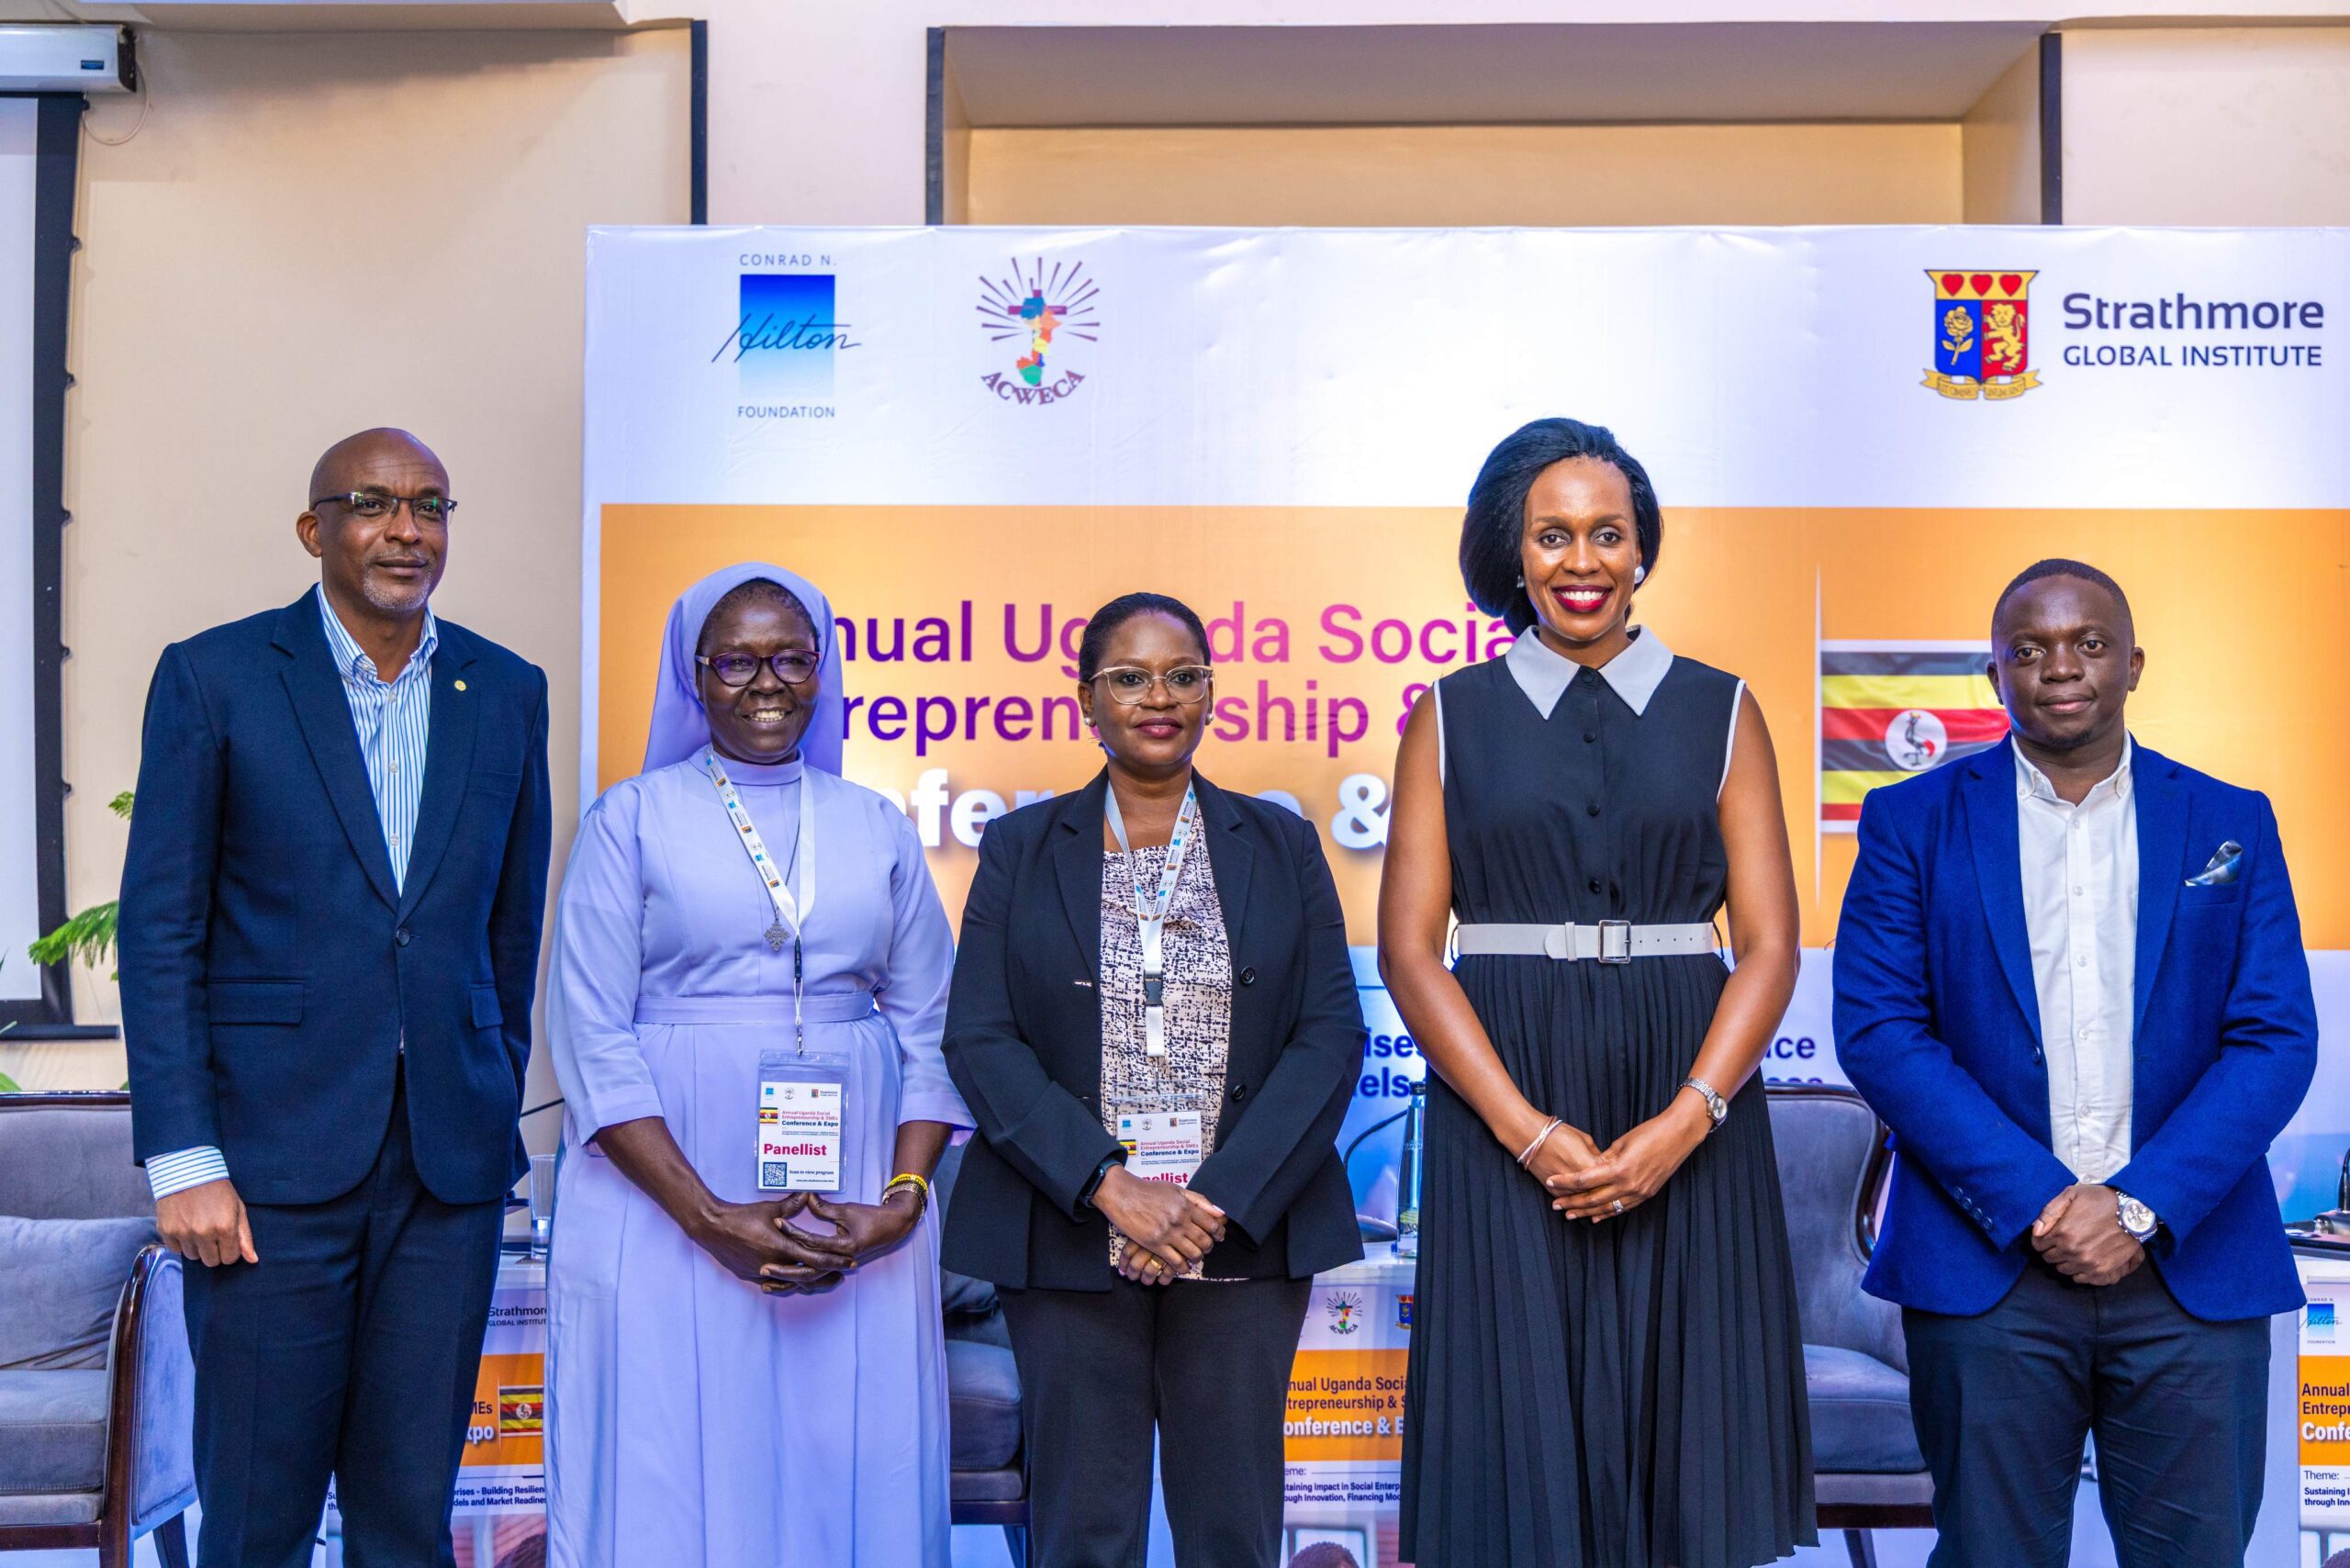
The consensus among financial executives is clear: liquidity exists within the market, but it remains locked away from traditional, informal operations. At the recent Annual Uganda Social Entrepreneurship and SMEs Conference and Expo in Kampala, financial leaders made it clear that digital currency channels, mobile money networks, and digital payment rails are no longer optional modernizations—they are now the fundamental prerequisites for institutional financing.


As commercial lenders pivot toward data-driven risk assessment, a business’s digital transaction history is directly dictating its survival rate in a highly competitive market. Speaking during a panel discussion, dfcu Foundation Executive Director Mabel Ndawula emphasized that entrepreneurs must evaluate their operational readiness through the strict lens of a lender. Lenders inherently look for tamper-proof evidence of consistent, predictable cash flows.
“Without automated digital records, assessing creditworthiness becomes impossible, leaving viable businesses cut off from necessary growth capital,” notes Ndawula.
To bridge this data deficit, financial tech providers argue that standard ecosystem integration is the priority. Speaking at the recent 8th Financial Technology Service Providers Association (FITSPA) Annual FinTech Conference in Kampala, tech sector leaders called for shared digital infrastructure and stronger data standards. Transitioning from fragmented apps to fully interoperable digital platforms is what will ultimately allow financial institutions to ingest alternative data and safely grant loans to underserved groups.

Data from the Bank of Uganda underscores a massive macro shift away from physical cash toward electronic money ecosystems:
Electronic money transaction values rose by 28% to reach Shs 366 trillion (approximately $100.3 billion).
Activity on the Uganda National Interbank Settlement System climbed 15.1% to Shs 1,025.7 trillion, demonstrating a highly liquid banking backbone shifting entirely to electronic channels.
Annual transaction volumes surged 17.3% to 9.1 billion transactions. Active mobile money accounts rose to 36.3 million, and telecom giant MTN Uganda alone reported processing Shs 195.5 trillion across its ecosystem.
The Sovereign Digital Frontier: To complement this growth, the central bank has advanced its feasibility studies for a Central Bank Digital Currency (CBDC). Initial Bank of Uganda reports signal that a programmable digital shilling could reduce cash-handling costs by 70.9% and accelerate economic growth by 1.1% to 2% by drawing the informal sector into the net.
Despite this rapid 30.3% average annualized growth in electronic commerce over recent years, physical currency in circulation still rose 12% to Shs 10 trillion in the 2025/2026 financial year. This persistence of cash illustrates why financial institutions are aggressively tightening the cash economy by lowering interbank check limits and introducing caps on over-the-counter cash withdrawals.

The push for rapid digital asset and transaction adoption is framed by stark macroeconomic realities highlighted during the summit. High business mortality rates are directly linked to structural informality. When 55% of the economy operates on unrecorded cash transactions, businesses cannot separate personal expenses from commercial revenue, leading to fatal cash flow mismanagement.
A core theme of the analysis focused on dismantling the misconception that formal financial tracking requires expensive enterprise resource planning (ERP) software. Gerald Otim, Chief Executive Officer of Ensibuuko, argued that the entry point to formalization is already in the pockets of most merchants. Otim pointed to existing mobile money networks, digital merchant wallet solutions, and integrated standard banking channels as the primary infrastructure for building an auditable trail.
Modern digital records power lending through three distinct mechanisms automatic ledgering,deriskingh the asset and credit scoring integration.


Every digital currency or mobile money transaction creates an immutable, timestamped receipt.This automated data compilation transforms volatile, invisible cash flows into structured, verifiable financial statements and Lenders can ingest these digital merchant payment histories directly into automated credit-scoring algorithms, bypassing the need for traditional physical collateral.
The summit panel—which also featured aBi Finance CEO Mona Muguma Ssebuliba and Prof. Dominica Dipio—concluded that the ability to generate clean financial data is now just as critical as the capital itself.
Through targeted enterprise development and digital literacy initiatives, institutions like the dfcu Foundation are actively training entrepreneurs to phase out physical cash dependency. Moving transactions onto digital rails is ultimately categorized not merely as a tech upgrade, but as a core risk-mitigation strategy. For Uganda’s 1.1 million MSMEs, transitioning to a digital transaction framework is the single most viable path to establishing bankability, surviving the critical five-year failure window, and scaling sustainably.


